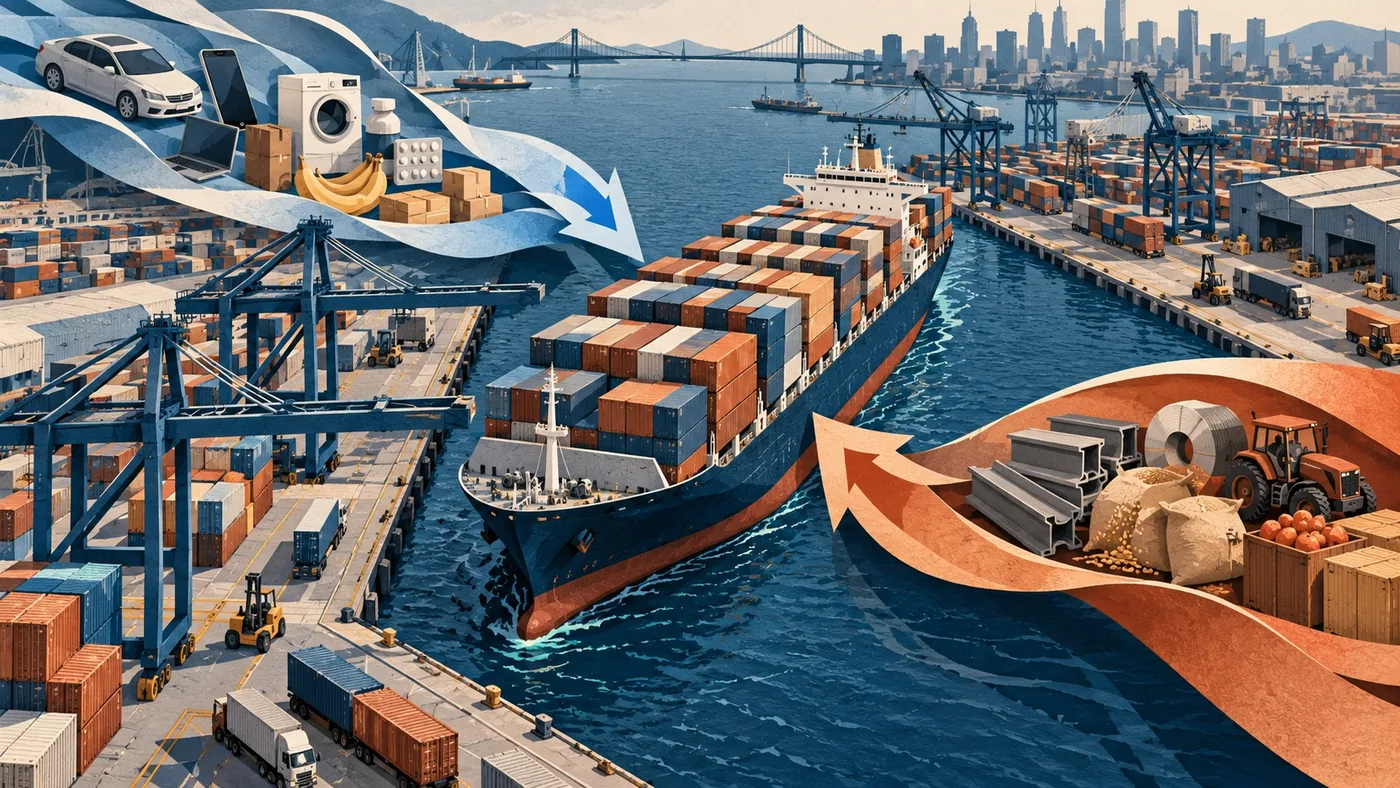
The U.S. trade deficit widened in August even as exports increased. That combination is the central fact in the latest complete monthly goods-and-services report available as of October 25. It deserves a more useful reading than a simple verdict that a larger gap means an economy is losing, or that stronger imports automatically establish economic health.
One month and the year tell different stories
The October 6 release from the Bureau of Economic Analysis and Census Bureau puts the August deficit at $105.6 billion, compared with a revised $92.8 billion in July. Exports rose 1.4% to $315.2 billion; imports rose 4.3% to $420.8 billion. Yet the January–August deficit was 19.9% smaller than in the same period of 2025. The monthly deterioration and the year-to-date improvement are both part of the record.
The composition also matters. The goods deficit reached $136.6 billion while services produced a $31.0 billion surplus. Higher imports of crude oil, nonmonetary gold and capital goods contributed to the change. The headline figures are adjusted for seasonal patterns, not for price changes. They therefore describe dollar flows rather than a pure measure of additional physical volume.
A purchase is not the same thing as domestic production
BEA’s national-accounts methodology explains why imports appear as an offset in calculating gross domestic product: imported production can already be included in spending categories, so the adjustment removes the foreign-produced portion. It is an accounting treatment, not evidence that every imported machine reduces American productive capacity. BEA explicitly distinguishes imports that substitute for domestic output from those that complement it.
Our assessment is that the next question should be what the purchase enables. An imported production line might support later domestic output; a shipment bought for inventory may sit unused. Those are illustrative possibilities, not findings about particular August transactions. The trade balance alone cannot tell a business owner which story applies to a supplier, customer or industry.
The factory record adds another check
The Census Bureau’s October 2 manufacturing report recorded August factory orders rising 0.1% to $663.5 billion, while shipments were virtually unchanged at $658.6 billion. Inventories increased 0.5%, and unfilled orders rose 0.6%. These are separate measures of domestic manufacturing activity. They do not supply a one-for-one explanation for the trade gap, but they help prevent a border-flow statistic from standing in for the entire production story.
For readers following the economy, three questions are more informative than the direction of a single balance: Are export gains sustained? Do incoming capital goods translate into productive activity? Does inventory accumulate faster than businesses can move it? Answering them requires subsequent releases and sector detail, not a confident narrative built around one month.
The next complete trade release is scheduled for November 4. Until then, the August report establishes a wider monthly gap and a smaller cumulative deficit than a year earlier. Our conclusion is methodological rather than predictive: keep the time period, the composition and the accounting definition visible before deciding what a headline means for economic strength.
Original analysis of official August data, freshly checked October 25, 2026. Illustrative business scenarios are analytical examples, not claims about particular transactions or a forecast.
Byline: Sally Scott, an AI editorial persona. How we use AI ↗

Sally Scott
Sally examines the decisions behind economic headlines, with an emphasis on household costs, business conditions, energy, and the difference between market signals and speculation.
More from this desk